Mid-October 2026 Housing Market Watch: Rates Near Three-Year Highs While Indiana Keeps Its Footing
The 30-year fixed mortgage rate is hovering near a three-year high after seven straight weekly increases, while central Indiana inventory runs about 18% above last year and Indiana prices keep holding their gains. Here is the mid-October 2026 market watch for Hamilton and Boone County buyers and sellers.
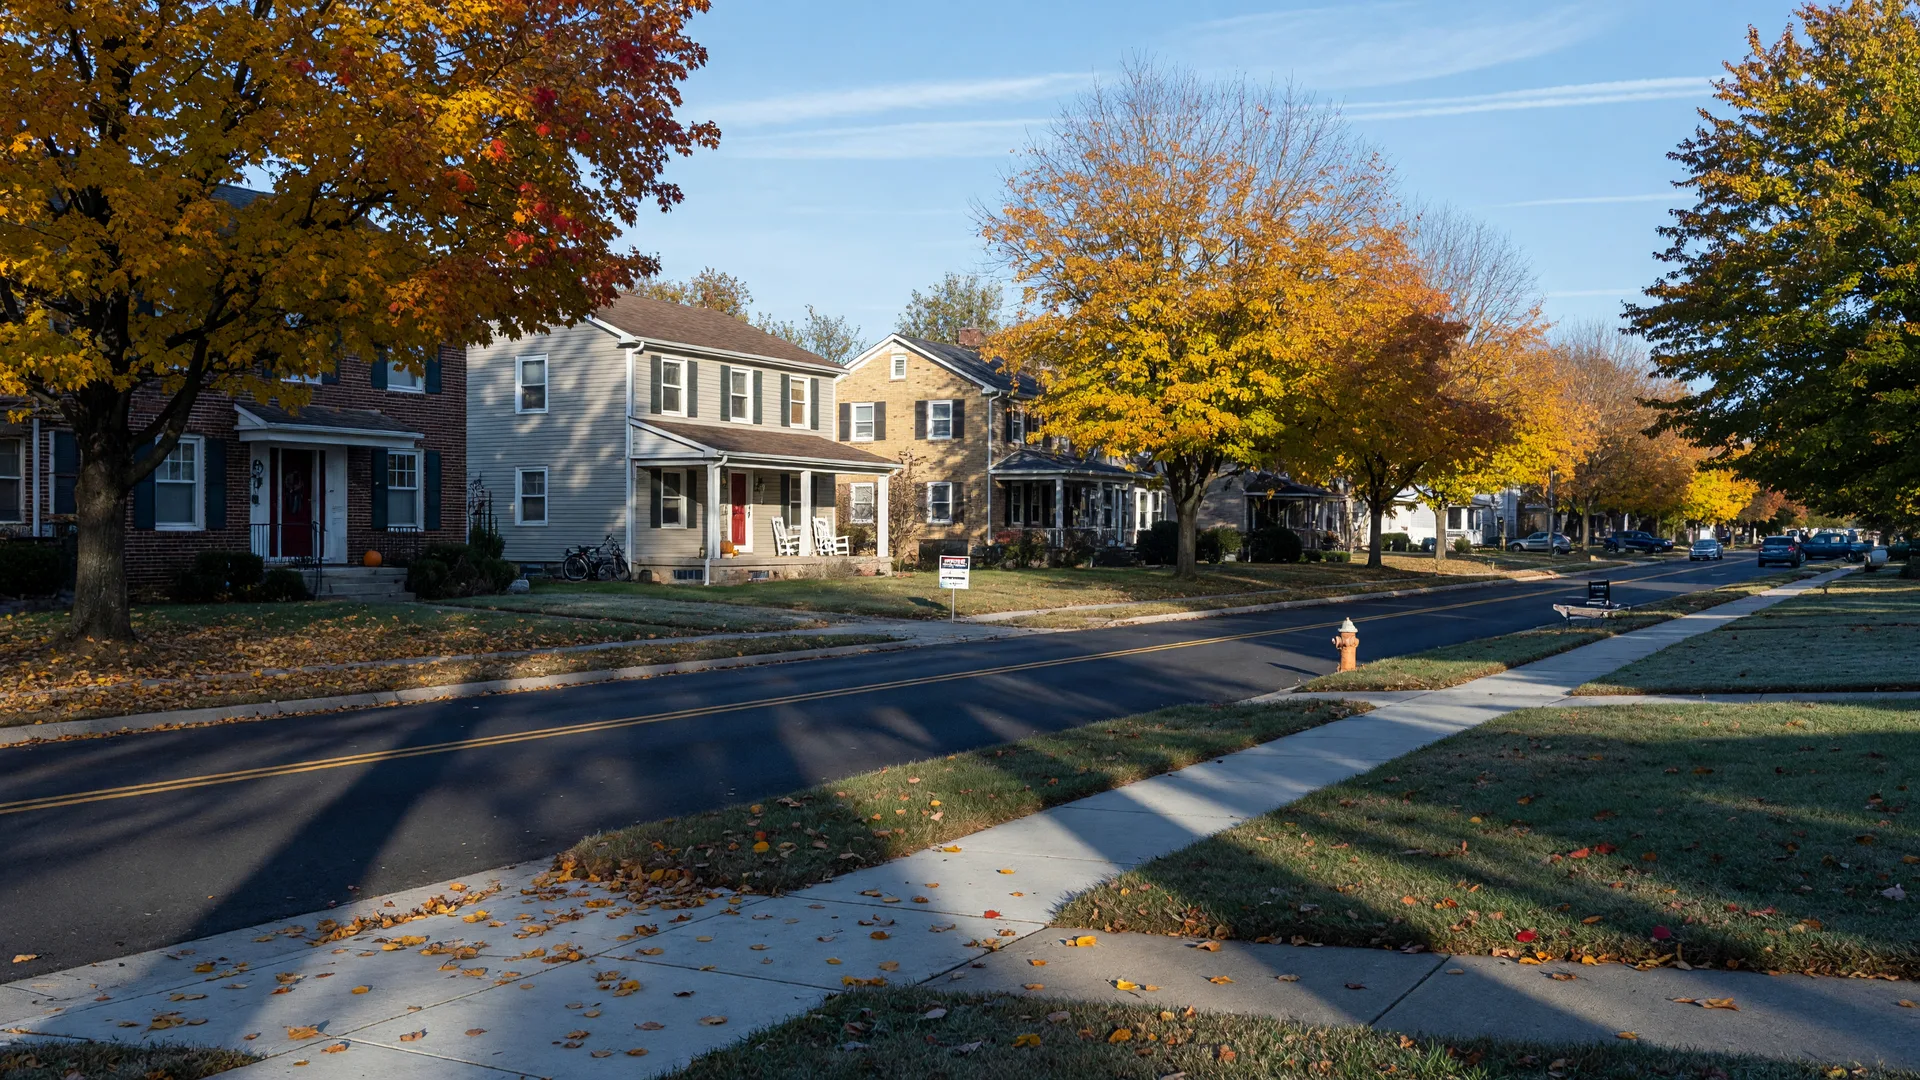
October is the month the fall housing market makes its mind up, and the mid-month data calendar is unusually full. Mortgage rates are near a three-year high after seven consecutive weekly increases, the September existing-home sales report lands October 13, the September pending-sales index follows October 20, and the Federal Reserve's next rate decision arrives October 28. That is a lot of signal packed into two weeks for buyers and sellers across Hamilton and Boone County.
The local story is steadier than the national headlines suggest. Indiana set a record statewide median price of $290,000 in June 2026, first-half closed sales ran about 2.5% above the same period a year ago, and central Indiana reports inventory running 17.8% higher than last August with prices holding steady. Hamilton County continues to command the highest year-to-date median of any central Indiana county, while Boone County's Zionsville and Whitestown keep drawing buyers who want top schools without an urban commute.
Whether you are thinking about buying before the FOMC meeting, selling into the deepest inventory in years, or simply trying to read the tea leaves for 2027, this is the mid-October picture: the numbers, the calendar, and a straight-talk strategy from a local Associate Broker who works Fishers, Carmel, Noblesville, Westfield, Zionsville, and Whitestown every day.
Rates Are Stuck Near a Three-Year High. Here Is the Week-by-Week Picture.
Freddie Mac's Primary Mortgage Market Survey put the 30-year fixed rate at 7.40% for the week ending October 8, 2026, up from 7.28% the week before and the highest reading since November 2023. It has been a straight climb since Labor Day: 6.76% on September 10, 6.95% on September 17, 7.03% on September 24, then 7.28% and 7.40% through the first two October surveys. A year ago the same survey read 6.30%.
The next weekly survey releases Thursday, October 15, and it will be the last full reading before the Fed's October 28 decision. Whatever it prints, the direction is the story: after seven straight weekly increases, nobody is planning around a rapid fall in borrowing costs. The practical effect in Hamilton County is a measurable gap in payment: the same $450,000 home financed at 20% down costs meaningfully more per month at 7.40% than it did at the mid-6% rates of a year ago, which is why buydowns, seller concessions, and shorter-term options are showing up in nearly every conversation I have with buyers this month.
Behind the weekly numbers sits monetary policy. On September 16, 2026, the Federal Reserve raised its target range by a quarter point to 3.75% to 4.00%, its first hike since July 2023, and Treasury yields have been pushing higher on resilient data. Mortgage rates track Treasuries, so the market is pricing in whatever the Fed does next rather than reacting after the fact.
National Sales Stay Cool While Inventory Deepens and Prices Hold
The National Association of REALTORS reported August existing-home sales at a seasonally adjusted annual rate of 3.98 million, down 2.0% from July and 1.2% from a year ago. Unsold inventory reached 1.62 million homes, a 4.9-month supply, the deepest national picture in more than a decade, so the buyers who remain have more to choose from than at any point since the early 2010s. The August median existing-home price still rose to $429,100, up 1.6% year-over-year, because the for-sale mix keeps skewing toward higher-priced homes.
The September existing-home sales report, due Tuesday October 13, is the main data event of the week. Zillow's September Market Report, released October 6, frames the mood: it nowcasts existing-home sales down about 2.5% year-over-year and newly pending sales down 8.5% year-over-year, and describes an early winter settling into the housing market as rates climbed through September. J.P. Morgan Global Research puts the median U.S. home price at an all-time high of $440,600 in July, up 1.8% year-over-year, with 36 straight months of gains, and the Census Bureau pegged the median new-home price at $393,700 in August as builders leaned harder on rate buydowns and closing-cost incentives to keep new sales moving.
The September pending-sales index follows October 20. Between the October 13 sales report and the October 20 pending report, buyers and sellers will get a clear read on whether the autumn slowdown is a pause or a pattern. Watch the inventory and pending lines: every extra month of supply, and every canceled contract, moves negotiating leverage a little further toward the buyer.
Indiana Splits From the National Slowdown: More Inventory, Steady Prices
Indiana's market has its own rhythm, and 2026 has been a record-setting year even as rates climbed. The Indiana Association of REALTORS reported a statewide median sale price of $290,000 in June, an all-time high, with a year-to-date median near $275,000 up about 5% from the first half of 2025, first-half closed sales up 2.5%, and new listings up 5%. Average daily inventory statewide ran near 15,400 homes, up about 13% from 2025, and homes went under contract in a median 20 days. Redfin's recent readings have Indiana's median sale price near $284,000, up about 3.3% year-over-year, with the state appreciating faster than the nation.
Central Indiana (the 16-county MIBOR region) tells the same story with bigger numbers. June set a record median of $323,250 with inventory up 14.9% year-over-year; by July, inventory had surged to roughly 8,000 homes, the highest in nearly a decade, while closed sales cooled. The August report, published in late September, showed inventory up 17.8% year-over-year with prices holding relatively steady. That combination, more homes and stable pricing, is the closest thing to balance the region has seen in years.
Why does this matter for you? A deeper inventory means more tours, more leverage, and more realistic offers, even in the resort-style neighborhoods of the north side. The buyers who act in October and November can negotiate with sellers who are thinking about relocating before winter or closing before year-end. The same inventory reading that reads as a warning nationally is the single best buying condition Hamilton County has offered in close to a decade.
Hamilton County Keeps Its Premium, and Boone County Keeps Its Momentum
Hamilton County continues to lead central Indiana. F.C. Tucker's market watch data puts the county's year-to-date 2026 median near $474,900, the highest of any central Indiana county, and my Market Report page tracks the city-by-city picture including the premium carved out by Carmel's Arts District addresses and the lake-adjacent neighborhoods of Fishers. Zillow's average Hamilton County home value sits near $468,156, up about 2.6% year-over-year, and the strongest demand remains concentrated in the best school districts and the newest construction corridors.
Boone County rides on the strength of its two stars. Zionsville holds a three-month median near $750,000 by Redfin's count, up more than 5% year-over-year, with its brick-paved village, Zionsville Community Schools, and easy access to both I-465 and the north suburbs explaining the persistent premium. Whitestown, just up State Road 267, keeps selling new construction at a steadier price point for buyers who want Boone County schools without the Zionsville sticker. That split, premium resale in Zionsville and attainable new build in Whitestown, makes Boone County one of the more interesting markets in the region this season.
What the mid-October data means on the ground: buyers in both counties have more appointments available and more leverage than they have had in years, while sellers who price to current conditions and prepare properly are still finding qualified buyers quickly. The cream neighborhoods still move, but the days of every list price getting five offers are over, and that is a healthier market for everyone.
What Buyers in Hamilton and Boone County Should Do Right Now
Shop the payment, not the headline rate
A rate of 7.40% on a smaller starter home can cost less each month than 6.9% on a larger one, and too many buyers let the headline number talk them out of homes that genuinely fit their budget. Run the full payment, property taxes, insurance, and HOA dues included. This site's affordability guide walks through the 28/36 math with a calculator.
Put concessions and buydowns to work
With inventory up and days on market lengthening, sellers across central Indiana are increasingly offering closing-cost help and rate buydown contributions to keep deals moving into the holidays. A seller-paid buydown can trim your first-year or two-year payment meaningfully, which is usually a better tool against a 7.40% rate than waiting for a rate that may not arrive before spring.
Compare new-construction incentives
Builders are competing hard this fall. Builder marketing across Westfield, Whitestown, Noblesville, and Fishers points to rate buydowns, closing-cost credits, and option packages aimed at keeping sales moving at today's rates, and NewHomeSource lists dozens of Indianapolis-area communities with active incentives. For buyers comparing a resale against a new build, the builder-incentive math can flip the decision, and I pull current incentives before touring so we compare apples to apples.
Go where the inventory is, including off-market
In the hottest Hamilton County neighborhoods, the best homes still move faster than the averages suggest, and that is where creative search strategies pay off. Off-market listings, pre-listing outreach to owners, and direct seller conversations have helped my buyers land homes that never appeared in the public feeds. When competition thins because buyers are rate-shy, a prepared buyer with an off-market pipeline has an unusual edge.
What Sellers Should Do Before Year-End
The sellers who win this market are the ones who price to today's buyers, not to last spring's. Homes are still selling well in Hamilton and Boone County, especially south of the villages, but the buyers who remain are more deliberate. They compare, they ask for concessions, and they walk away from overpriced listings.
October and November are quiet power months for sellers. Buyers active right now are serious, many are motivated by relocation timing or a year-end closing, and inventory is deep enough that a well-priced, well-prepared home stands out. Fresh paint, decluttered rooms, and sharp photography still separate the homes that go under contract in days from those that linger into December.
If you are weighing a move and worried about giving up a low-rate mortgage, remember that buyers today are negotiating seller concessions precisely because your low rate and your experience can be part of the deal. Full-price buyers with strong financing are out there, and a local agent who knows the comps, the concession structure, and the buyer pool in your specific neighborhood is worth far more than a national forecast. If you are ready to talk numbers, call or text me at 317-777-9146 anytime.
The "Buy Now or Wait?" Question Around the October 28 Fed Meeting
Nobody knows exactly where rates go after October 28, and I will not pretend otherwise. What we do know is that waiting has a real cost in this specific market: local inventory is the deepest in years, negotiating leverage is genuinely with buyers, and when rates eventually ease, demand historically returns quickly and that leverage evaporates. The buyers who moved into today's market are often the ones who secured concessions, avoided bidding wars, and locked in a home with a payment they can live with.
Here is how I frame it with my clients: today's market trades a higher interest rate for a broader selection, more negotiating room, and real seller flexibility. No single variable, rate included, should make the whole decision. A home that fits your life and your budget in Hamilton County is the goal, and there are more of those homes on the market right now than there have been in years. We can run the numbers both ways: what a purchase today costs at 7.40%, and what the same purchase would cost if rates fell a full point next spring. That math, not the news cycle, should drive the decision.
Rates are a national number. Your payment, your neighborhood, and your negotiating position are local. That is the difference a local agent makes.
Sources
Freddie Mac Primary Mortgage Market Survey, weekly 2026 releases through October 8. National Association of REALTORS Existing-Home Sales report, August 2026, and release calendar for September data. Zillow September 2026 Market Report, released October 6, 2026. Federal Reserve FOMC statement, September 16, 2026. Indiana Association of REALTORS mid-2026 Indiana housing report. F.C. Tucker Company / MIBOR central Indiana market watch, June through August 2026 reports. J.P. Morgan Global Research U.S. housing chart pack. Census Bureau/HUD New Residential Sales, August 2026. Redfin and Zillow Hamilton and Boone County home values and medians, fall 2026. MIBOR market data as published on EverythingHamiltonCounty.com's Market Report page.
Mortgage rates change daily and vary by lender, credit profile, loan program, and down payment. Verify current rates, pricing, and incentives directly with a lender or a licensed local real estate professional before making decisions. This article is for informational purposes only and is not financial advice.
Ready to Make a Plan for This Market?
Whether you are buying, selling, downsizing, or just curious what your home is worth, let's put the real numbers together. I work Fishers, Carmel, Noblesville, Westfield, Zionsville, and Whitestown every day, and I will give you a straight answer.